债券交易员面临被逼平空头头寸的风险,因为他们重新建立看跌头寸,而围绕人工智能的新担忧以及一系列技术故障重新点燃了避险情绪。
Bond traders risk facing a short squeeze after reloading bearish positions, as renewed jitters around artificial intelligence and a spate of technical disruptions reignite a flight to safety.
过去一周,美联储的政策立场转为鹰派,帮助抑制了本月初曾将10年期国债收益率压低至4.81%的初步避险需求,使得长期存在的国债空头头寸基本保持不变。美国银行的策略师警告称,这正迅速成为市场的“痛点交易”。
A hawkish shift in the Federal Reserve’s outlook over the past week helped mute a nascent haven bid that sent 10-year bond yields as low as 4.81% earlier this month, leaving longstanding Treasury shorts largely intact. That’s fast becoming the market’s pain trade, strategists at Bank of America warned.
“上周抛售后,随着动能重新转向有利于空头的方向,空头头寸获得了喘息之机,”美国银行策略师周一在一份报告中写道,并补充称,一些动能驱动的账户最近重新进入空头头寸,但“程度较小”。策略师表示,在避险浪潮中,这些看跌头寸容易受到快速反转的影响。“空头头寸仍然是更集中的头寸,如果利率上涨,则可能是痛点交易,但近期价格走势后,门槛更高,”他们表示。
“Shorts saw a reprieve as momentum moved back in their favor after last week’s selloff,” Bank of America strategists wrote in a note Monday, adding that some momentum-driven accounts have recently re-entered short positions, although “to a smaller extent.”The bearish positions are vulnerable to quick reversals amid flight-to-quality waves, the strategists said. “Shorts remain the more concentrated position and the likely pain trade if rates rally, but the threshold is higher after recent price action,” they said.
周二,这一风险显而易见。美国国债迅速扭转了因10月美国零售销售超预期而引发的损失,此前有报道称,国家安全局用于内部通信的一个高度机密网络出现故障。这是自上周以来影响微软公司和多家银行的一系列中断事件中的最新一起,引发了对广泛中断的担忧。现券债券上涨,收益率跨期限降至盘中低点,而期货成交量飙升至当日最高。
That risk was on display Tuesday. Treasuries quickly reversed losses led by better-than-expected US retail sales in October, after a report that a highly classified network used by the National Security Agency for internal communications was down. It was the latest in a series of outages that affected Microsoft Corp. and several banks since last week, stoking fears of widespread disruptions. Cash bonds rallied, sending yields to session lows across maturities, while futures volumes spiked to the highest of the day.
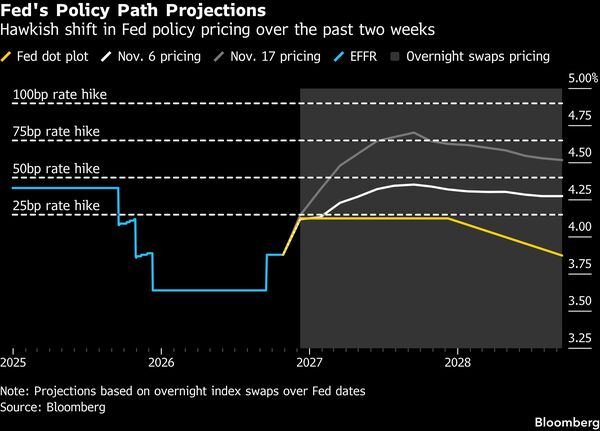
这些走势发生在对美联储12月9日会议上加息半个百分点的尾部风险对冲需求激增之后,此前10月的通胀数据高于预期,以及理事克里斯托弗·沃勒的言论提升了大幅加息的可能性。
The moves follow a surge in demand to hedge against the tail risk of a half-point interest rate hike by the Federal Reserve at the Dec. 9 meeting, after hotter-than-expected inflation data for October and remarks by Governor Christopher Waller raising the prospect of an outsized increase.
交易员开始运用期权策略,押注次级隔夜融资利率(SOFR)在下个月政策公告后的走势。12月SOFR期权已成为一种受欢迎的对冲工具,将于今年最后一次会议结束后两天到期。
Traders opened up the options playbook with bets around where the Secured Overnight Financing Rate will be after next month’s policy announcement. The December SOFR options have proved a popular hedging tool, expiring just two days after the last meeting of the year.
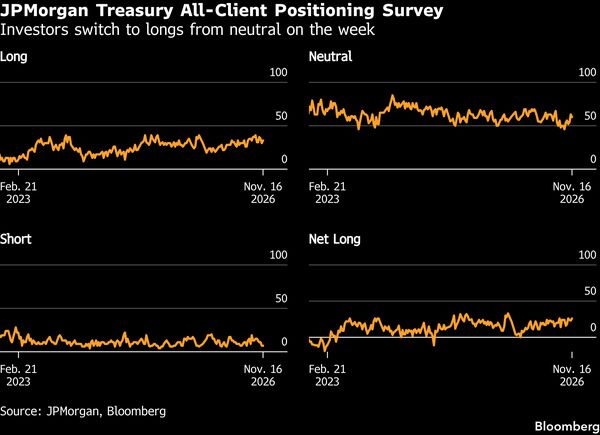
在现货市场,出现迹象表明,拥挤的空头头寸可能开始平仓。截至11月16日当周,摩根大通国债客户调查显示,纯空头头寸维持在约三个月来的最低水平,而纯多头头寸则有所上升,交易员从中性头寸转向多头。
In the cash market, signs are emerging that crowded short positions may be starting to unwind. In the week up to Nov. 16, a JPMorgan Treasury client survey showed outright shorts positions remaining at their lowest in about three months, while outright long positions rose in a switch out of neutrals.
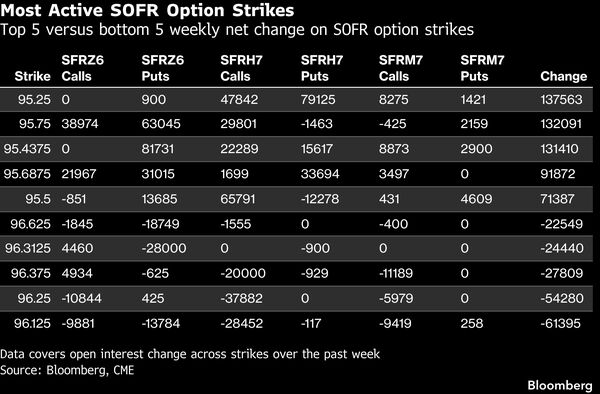
彭博策略师观点……“数据走强,加上国债与油价及AI驱动的风险规避情绪脱钩,表明一种新的叙事正在形成,即亏损交易越来越可能是收益率上升。”——迈克尔·鲍尔,宏观策略师,市场直播。以下是过去一周利率市场其他定位指标的概述:在SOFR Dec26、Mar27和Jun27期权中,Mar27看涨期权行权价新增了相当数量的风险敞口,原因是过去一周SFRH7 95.25/95.50/96.00看涨期权碎片组合头寸大量建立,这些头寸通过SFRH7 96.00/96.25看涨期权价差进行买入。
What Bloomberg Strategists say...“Stronger data, combined with Treasuries’ decoupling from oil and AI-driven risk aversion, suggest a new narrative where the pain trade is increasingly higher yields.”—Michael Ball, Macro Strategist, Markets LiveFor the full analysis, click here. Here’s a rundown of other positioning indicators across the rates market over the past week: Across SOFR Dec26, Mar27 and Jun27 options, a decent amount of new risk was added in Mar27 call strikes, due to heavy new positioning in SFRH7 95.25/95.50/96.00 broken call flies over the past week, which were bought with SFRH7 96.00/96.25 call spreads.
在相同期限内,SFRH7 95.50/95.75/96.00看涨期权碎片组合在近期交易中也颇受欢迎。此外,近期交易中还出现了SOFR Dec26 95.75看跌期权的直接买入,增加了该行权价的未平仓合约。上周这些看跌期权以7.25的价格买入,周一直接买入流动继续,买入价为6.75。
In same tenor, SFRH7 95.50/95.75/96.00 call flies were also popular over recent sessions. There has also been outright buying in SOFR Dec26 95.75 puts over recent sessions, adding to open interest in that strike. Last week they were bought at 7.25 while the outright flow continued Monday via buyer at 6.75.
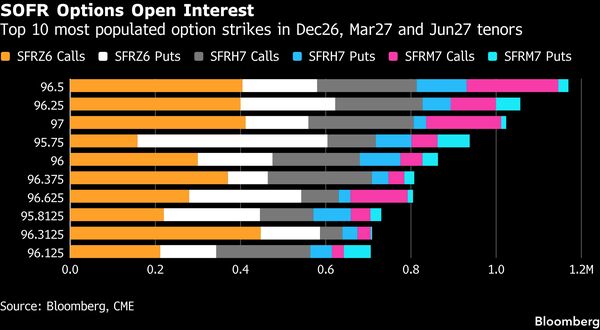
在Dec26、Mar27和Jun27 SOFR期权中,96.50行权价仍是最拥挤的行权价,近期头寸包括SFRM7 96.50/97.25 2x3看涨期权价差,这些头寸是通过卖出Mar27 96.25/97.00 2x3看涨期权价差来建立的。该行权价附近的近期流动表现为稳定买入Jun27 96.50/97.00/97.50/98.00看涨期权铁鹰组合。
Across Dec26, Mar27 and Jun27 SOFR options, the 96.50 strike remains the most populated, where recent positioning has included SFRM7 96.50/97.25 2x3 call spreads, which were bought vs selling Mar27 96.25/97.00 2x3 call spreads. More recent flow around the strike has been steady buying of Jun27 96.50/97.00/97.50/98.00 call condors.
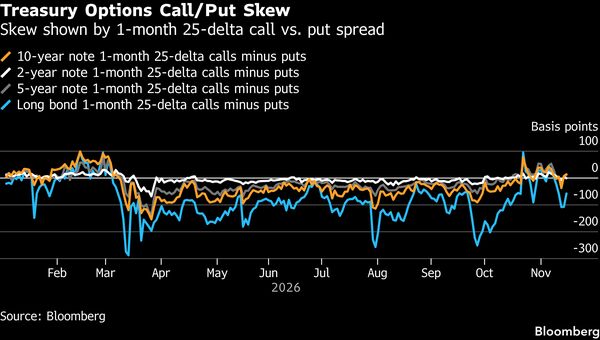
对冲国债期权的溢价仍偏向看跌期权,集中在期货合约的远月合约,尽管在最近几个交易日已略微接近中性。随着10年期国债收益率重新升至5%以上,最近的国债期权资金流向在12月合约上呈现混合态势。显著交易包括通过12月105.00/105.50的1x2看跌期权价差进行下行押注,而上行押注则包括12月106.00/107.00看涨期权价差。
The premium to hedge Treasury options remains skewed toward puts in the long end of the futures strip, although it has edged closer to neutral over recent sessions. With 10-year yields back above 5%, recent flows in Treasury options have been mixed around the December tenor. Standout trades have included downside via December 105.00/105.50 1x2 put spreads while upside has included December 106.00/107.00 call spreads.
在截至11月16日的一周内,投资者从中性头寸转为多头,空头头寸保持不变。纯多头头寸上升3个百分点,中性头寸下降相同幅度。该调查继续显示,纯空头头寸为自8月17日以来的最低水平。
In the week up to Nov. 16, investors switched to longs out of neutrals with shorts unchanged. Outright long positions rose by 3 percentage points, with neutral dropping the same amount. The survey continues to show lowest outright shorts since Aug. 17.