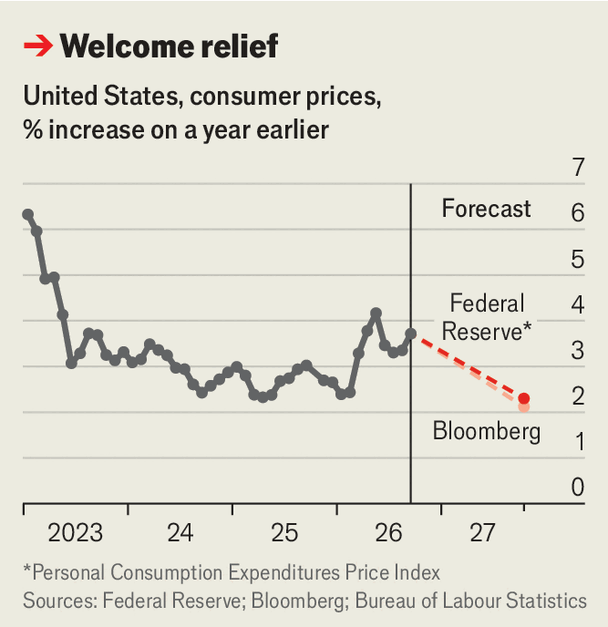
你可以称之为倒霉。美国通胀率现已连续近六年高于美联储 2% 的目标。每当通胀似乎即将回落时,唐纳德·特朗普总会做些什么把它推回去,无论是“解放日”关税还是挑起与伊朗的战争。
You could call it bad luck. Inflation in America has now been above the Federal Reserve’s 2% target for nearly six years. Each time it looked like it might be dipping back down, Donald Trump has done something to send it up again, whether that be “Liberation Day” tariffs or starting a war with Iran.
因此,对 2027 年通胀降温的任何期待,都必须建立在这样一个认知之上:特朗普仍是总统,且完全有能力再次让物价飙升。即便如此,2027 年仍可能是美国终于摆脱后疫情时代通胀的一年。这种乐观的一个理由是,共和党在中期选举中惨败,可能缩小了特朗普式混乱干预的进一步空间。
So any hopes for lower inflation in 2027 must be tempered by the knowledge that Mr Trump is still president, and more than capable of sending prices soaring again. Even so, 2027 could be the year that America finally sees off its post-pandemic inflation. One reason for such optimism is that the Republicans’ drubbing in the midterms may have narrowed the scope for further chaotic Trumpian interventions.
这提出了一个诱人的可能性:决定美国物价走向的将是通胀的常规经济驱动因素,而非特朗普。在这方面,有理由期待取得突破。美联储已从降息转为加息,并发出 2027 年进一步加息可能性颇大的信号。迄今为止,特朗普去夏天任命为美联储主席的凯文·沃什——尽管大谈“制度变革”——基本表现得像一位普通的央行行长。
That raises the enticing possibility that the usual economic drivers of inflation, rather than Mr Trump, will determine what happens to prices in America. And on that front there is reason to hope for a breakthrough. The Fed has moved from cutting interest rates to raising them, and has signalled decent odds of further rises in 2027. So far, Kevin Warsh, whom Mr Trump appointed as Fed chair last summer, has—despite his grandiose talk of “regime change”—largely behaved like an ordinary central banker.
货币政策或许不算紧缩,但也不宽松。特朗普“一项宏伟美妙法案”带来的减税大放送已经落地,因此 2026 年同样帮助维持通胀的财政刺激应当会逐渐消退。失去对国会的控制权后,特朗普将难以再提供同等规模的福利。
Monetary policy may not be very tight, but nor is it loose. The splurge of tax giveaways from Mr Trump’s “One Big Beautiful Bill” has happened, so the fiscal boost that also helped sustain inflation in 2026 ought to fade away. Without control of Congress, Mr Trump will struggle to offer further goodies on that scale.
美国就业市场也不太可能成为通胀来源。失业率按历史标准虽低,但仍高于几年前的水平。失业人数与职位空缺的比率——衡量劳动力市场状况的常用指标——处于近期平均水平左右。工资增长甚至显得偏低。
America’s jobs market is not likely to be a source of inflation either. The unemployment rate is low by historical standards, but still above where it was a few years ago. The ratio of unemployed people to job vacancies, a common measure of labour-market conditions, is around its recent average. Wage growth is, if anything, looking low.
通胀下降可能只是短暂喘息 美国经济的某些领域当然依然火热。GDP增长一直保持在健康的2%。人工智能投资蓬勃发展。股价一路飙升。即使债券收益率大幅上升,整体借贷条件依然宽松。即便没有石油危机,所有这些因素在2026年也可能足以推高通胀。除非人工智能繁荣出现不受欢迎的逆转,否则这些支撑因素在2027年应该会持续。
The dip may be only a short reprieve Pockets of America’s economy are certainly still looking hot. GDP growth has been running at a healthy 2%. Investment in artificial intelligence is booming. Share prices have been on a tear. Even with a big rise in bond yields, overall borrowing conditions have stayed buoyant. All that might have been enough to raise inflation anyway in 2026, even without the oil crunch. Those supports should persist during 2027, barring an unwelcome unwinding of the AI boom.
那么,综合来看,通胀下降的可能性看起来不错。它能降到2%吗?投资者担心,美联储已经学会与略高于目标的通胀共存。沃什先生坚称:“这个委员会任内,绝无所谓的隐性软性目标。只有一个目标,就是2%。”那么,要达到2%可能有些困难,但接近2%应该是可能的。不过,普通美国人可能察觉不到。他们愤怒,并将“可负担性”当作当下的政治焦点,原因是物价绝对水平远高于2019年。
Pull it all together, then, and the odds of inflation falling look good. Will it go all the way to 2%? Investors fret that the Fed has learned to live with inflation a little above its target. Mr Warsh has insisted that “There is no soft implicit target—not on this committee’s watch. There’s only a target, and it’s 2%.”Hitting 2% may be a stretch, then, but getting close ought to be possible. Ordinary Americans may not notice, though. The reason they are incensed, and have made “affordability” the political cause of the moment, is that the absolute level of prices is much higher than in 2019.
现在降低通胀无法止住这种痒。工资增长跑赢通胀这一事实也无济于事。但只要等得足够久,记忆就会淡去,只是不会在2027年。
Lower inflation now will not scratch that itch. Nor will the fact that wage growth has more than kept up with inflation. But wait long enough and memories will fade, just not in 2027.
然而,通胀下降可能只是短暂喘息。政府借贷不可持续,2027年发生的事情不太可能改变这一点。但债务危机需要很长时间才能酝酿。最终,政府可能会认为,通过通胀贬值债务比提高税收或削减受欢迎的社会项目要少痛苦。但那是明年的事了。■
The dip in inflation may be only a short reprieve, however. Government borrowing is unsustainable and nothing that happens in 2027 is likely to change that. But debt crises take a long time to brew. Eventually the government may decide that devaluing its debts through inflation would be less painful than raising taxes or cutting popular social programmes. But that is a problem for another year. ■