发布于:2026-11-20T02:00:20+08:00美元可能正处在一个霸权新时代的门槛上,这应当能让怀疑论者闭嘴。但其重焕的韧性也伴随着波动加剧。这使各经济体越来越容易受到美国政策突变和科技行业快速演变的冲击。德意志银行将其称为“芯片美元”,由人工智能热潮推动。
Published: 2026-11-20T02:00:20+08:00 The dollar may be on the cusp of a new era of hegemony that should silence the skeptics. But with its renewed resilience also comes increased volatility. That leaves economies increasingly vulnerable to lurches in US policy and the rapid evolution of the technology industry. It’s what Deutsche Bank AG has dubbed the “chip dollar,” driven by the boom in artificial intelligence.
这一说法让人想起1971年理查德·尼克松终结布雷顿森林固定汇率体系后涌入、支撑美元地位的石油美元。那次体系瓦解让许多人宣称美元的好日子已经过去。然而,这种主导地位只是进入了另一个阶段。
The term recalls the influx of petrodollars that buttressed the currency after Richard Nixon ended the Bretton Woods system of fixed exchange rates in 1971. The break led many to pronounce the dollar’s best days were behind it. The dominance was, however, merely entering another phase.
我们可能正在目睹类似的转变,但有一些重要差异。如今,科技行业正吸引大量与人工智能相关的投资,而长期以来美国国债一直是美元流动的主要载体。
We could be witnessing a similar transition, with some important differences. Today, the technology business is attracting massive AI-related investment, whereas Treasuries have long been the mainstay for dollar flows.
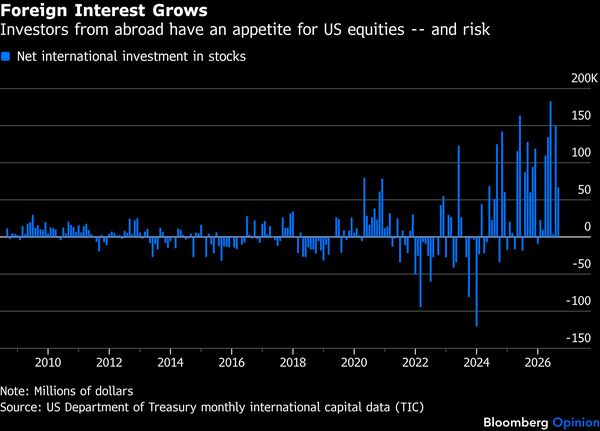
如果这一趋势持续,很可能意味着外国对美国股票的需求将进一步扩大。去年美国股票录得至少十年来最大规模的资金流入,增长约130%,超过7000亿美元。2026年有望至少追平这一数字。这轮抢购在截至6月的三个月内升至约4270亿美元,创下季度纪录,随后在截至9月的三个月中放缓。海外持有的美国国债存量虽达9.2万亿美元,但自2月以来已有所回落。
If that holds, it’s likely to mean still greater foreign demand for US equities, which last year enjoyed the biggest inflow in at least a decade, rising about 130% to more than $700 billion. They are on track to at least equal that figure in 2026. The buying spree rose to around $427 billion in the three months ended June, a quarterly record, before slowing in the three months ended September. The international stockpile of Treasuries, while amounting to $9.2 trillion, has retreated since February.
然而,股票虽然可能带来丰厚回报,却也波动不定,风险远高于债券。因此,美元的波动可能更大,并对全球经济健康和金融稳定产生更重大的影响。
But while stocks can be lucrative, they are also volatile — and far riskier than bonds. The dollar's fluctuations may, as a result, become greater and have more significant impact for global economic health and financial stability.
资本流动的波动既能托举国际市场,也能将其颠覆。视美元波动的程度而定,较小经济体将不得不加息或降息以稳住本国货币,而不顾国内经济状况。印度尼西亚即为一例:其经济低迷,却被迫推高借贷成本,以防盾币崩盘。(该国的困境因国内决策反复无常而加剧。)“石油美元”论点的依据,在于中东产油国在1973年赎罪日战争后推高油价,从而享受到出口收入激增。由于国内缺乏足够大规模的投资渠道,大量现金红利最终流入了美国国债。
Swings in capital flows can buoy international markets while also upending them. Smaller economies will need to raise or slash interest rates to steady their currencies, regardless of domestic conditions, depending on the extent of dollar gyrations. One case in point is Indonesia, whose economy is lackluster and borrowing costs have been pushed higher to prevent a collapse in the rupiah. (The country’s predicament has been compounded by erratic decision-making at home.) The petrodollar thesis hinged on the surge in export earnings enjoyed by oil producers in the Middle East, which ratcheted up prices after the 1973 Yom Kippur War. Much of the cash bonanza ended up in Treasuries as there weren't sufficiently large investment options at home.
这些资金流入反过来帮助为美国开支提供了资金,包括全球防御保护伞的费用——保守的海湾国家在其庇护之下,欧洲、亚洲和太平洋盟友亦然。“美国治下的和平”部分由向美国出售商品的国家买单,它们将收益回流投资,以换取一定程度的保护。
Those inflows, in turn, helped fund American spending, including on the global defense umbrella under which conservative Gulf states sheltered, in addition to allies in Europe, Asia and the Pacific. Pax Americana was bankrolled in part by countries selling stuff to the US, and recycling the returns in exchange for a degree of protection.
在最新的范式中,亚洲扮演了类似中东的角色。该地区的出口强国因半导体和电子产品需求旺盛,从海外出货中赚取巨额收益——美国是最大买家之一。例如,韩国芯片出口在10月同比激增260%;今年海外客户采购韩国商品超过1万亿美元。马来西亚企业海外销售创纪录,台湾则享受数十年来最佳经济状况。
In the latest paradigm, Asia takes on a role akin to the Middle East. The region’s export powerhouses are racking up major earnings from shipments abroad, courtesy of demand for semiconductors and electronics — and the US is among the biggest buyers. South Korean chip exports, for example, climbed 260% in October from a year earlier; overseas customers bought more than $1 trillion of Korean goods this year. Overseas sales by companies in Malaysia are at a record, while Taiwan is enjoying its best economic conditions in decades.
该地区不断扩大的贸易顺差需要安放去处。随着人工智能开发的资本支出蓬勃发展,美国成为极具吸引力的押注对象。从某种意义上说,顺差国家将在押注自己。至少,这是在押注它们对美国的持续重要性——以及它们对美国的依赖。
The region's widening trade surpluses need a home. And with capital spending on AI development flowering, America is an enticing bet. In some ways, the surplus countries will be betting on themselves. At the very least, it's a wager on their continued relevance to the US — and their dependence on it.
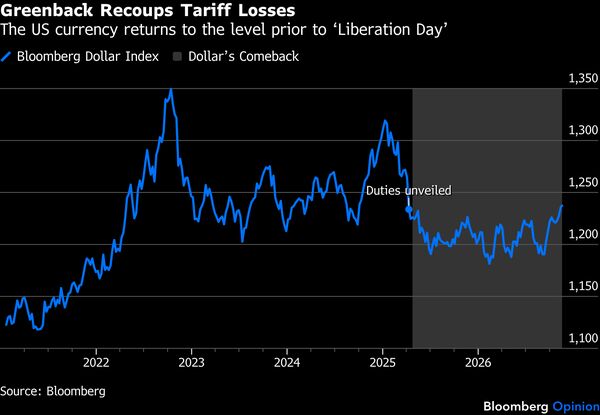
唐纳德·特朗普总统对向亚洲作出的外交和军事承诺表示怀疑,此外他还频繁抨击北约成员国。这引发了人们对美国持久力的诸多担忧,以及对华盛顿影响力衰落之后可能发生什么的焦虑。这种观点在特朗普政府实施全面关税后广为流传,但它误读了经济实力的起伏。挑战就在于此。
President Donald Trump has expressed skepticism about diplomatic and military commitments to Asia, in addition to his frequent broadsides against NATO members. That's led to much hand-wringing about American staying power and anxiety about what might follow the eclipse of Washington's influence. That view, widespread after the Trump administration imposed sweeping tariffs, misreads the ebbs and flows of economic strength. Therein lies the challenge.
德意志银行的马利卡·萨奇德瓦在本周的一份报告中写道:“芯片作为美元主导地位驱动力的崛起,是美国实力根本来源变化的征兆——从地缘政治领导力转向技术领导力。”
“The rise of chips as a driver of dollar dominance is a symptom of change in the ultimate sources of US power — from geopolitical to technological leadership,” Mallika Sachdeva at Deutsche Bank wrote in a report this week.
美元也因市场预期美联储将加息而获得提振,它经历过起起落落,未来还会有更多起伏。但美元已深深嵌入商业结构以及为其服务的金融体系之中。在各国央行的储备资产中,美元令竞争对手相形见绌。它在商业开票和跨境贷款中占据巨大份额。如今,这一足迹延伸到了人工智能领域。
The dollar, which is also getting a lift from expectations the Federal Reserve will hike interest rates, has had its ups and downs, and there will be more. But it's embedded in the fabric of business and the financial system that serves it. In central bank reserve holdings, it dwarfs competitors. It accounts for massive chunk of commercial invoicing and of cross border loans. Now, that footprint extends to AI.
抛售美国?亚洲经济体与美元和美国经济的紧密程度,可能比一段时间以来都要高。
Sell America? Asian economies may be more tightly wedded to the greenback and the US economy than they have been for some time.